The medical corporation saves you tax. It can also create some of your hardest financial questions.
What physicians say
“Working with Maxim was an eye-opening experience. I’m ahead of schedule and planning on retiring a lot sooner than expected. Their guidance has been practical, clear, and genuinely life-changing.”
Luke Green, MD
The half-executed financial life
Most physicians we meet don’t have a bad financial plan. They have half of one. Busy people get pitched constantly, say yes to a few things, and end up with pieces that don’t talk to each other. We coordinate the whole picture.
The decisions physicians bring us
- Salary or dividends, and whether the default answer still holds at your income
- Investment income building up inside your corporation and eating into your small business deduction, which means more of your practice income taxed at the higher rate
- Whether to incorporate at all, or restructure what you already have
- An accountant, an MD-focused investment advisor, and a lawyer, and nobody coordinating the three
- A move: a new province, a US opportunity, or leaving Canada entirely
- Winding down your practice, and what retirement looks like when most of your wealth lives inside a medical corporation
How we’re different from physician-focused investment firms
Most firms that specialize in physicians are selling something: a portfolio, a policy, a product. The advice comes attached to the sale.
We’re fee-only. We sell nothing but the work. Our job is coordination: your corporation, your taxes, and the advisors you already have. You pay a fee for exactly that.
Our partnership with Physician Empowerment
Physicians ask other physicians first. Many of our physician clients find us through Physician Empowerment, a Canadian education group founded by two practicing doctors to teach physicians finance, practice management, and wellness. We know their community, and they know our work.
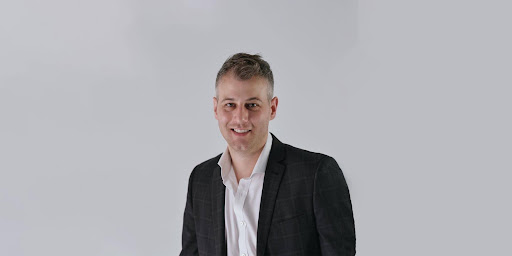
Dr. Kevin Mailo. Emergency physician in Edmonton and co-founder of Physician Empowerment. Kevin has taught physicians for nearly two decades and is known for making complex topics stick.
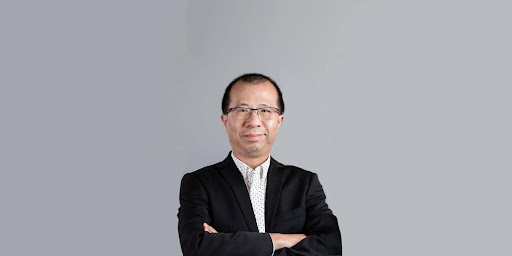
Dr. Wing Lim. Family physician in Alberta for more than twenty years and co-founder of Physician Empowerment. Wing built one of Canada’s largest independent medical facilities and teaches practice management and business development to fellow doctors.
Physicians entering and leaving Canada
A US opportunity looks simple until the corporation gets involved.
Leaving Canada triggers departure tax: the day you go, Canada treats most of your investments as sold, including your shares in the medical corporation. The corporation needs a plan of its own. Wind it up or restructure it as you transition your practice. The right answer depends on timing you can’t redo. And the corporation is rarely the whole job. Most physicians have built real wealth by the time a US move is on the table: investments, real estate, an estate plan. Each piece needs its own cross-border plan, because the move carries real opportunities and real traps. That planning starts before the licence paperwork does.
It runs the other way too. Canada actively recruits physicians from abroad, and a lot of physicians arrive with no idea how the tax system works here. Whether you’re entering Canada or leaving it, cross-border planning before the move beats cleanup after it.
Already mid-move? The sequencing still matters. Some decisions are behind you, but the ones ahead are usually the bigger ones.
Questions physicians ask us
Should I pay myself a salary or dividends from my medical corporation? There’s no universal answer, which is why the generic advice fails at higher incomes. The right mix depends on your RRSP room, CPP position, the corporation’s passive income, and your province. It also depends on the corporation’s own picture: refundable tax balances, payroll costs, shareholder advances, corporate surpluses, and what your shares will one day mean for your estate. A great model always starts with shareholder compensation planning. We build that model with your numbers and show you the difference in dollars.
Do I need a financial planner if I already have an accountant? They do different jobs. Your accountant handles taxes and compliance. A planner decides the overall strategy: corporate structure, investment mix, tax effectiveness, exit plan, and how they all fit together. Most people assume their accountant is doing that work. In our experience, they rarely have the time, and often not the mandate. Most professionals operate in silos, and the biggest problems and the biggest opportunities live in the gaps between advisors.
What happens to my medical corporation if I leave Canada? Leaving triggers a departure tax: Canada treats most of your property as sold at fair market value the day you become a non-resident, including your corporation shares. The corporation needs its own plan before you go. The options narrow sharply after you’ve moved.
What does fee-only mean? We’re paid by clients, and only by clients. No commissions. We don’t sell products or take referral fees either. When we recommend something, the only thing we earn from it is the fee you already agreed to.
What opportunities am I missing? Usually a few, and they’re rarely exotic. The common ones are a salary and dividend mix set years ago and never revisited, investment income quietly grinding down the small business deduction, and a corporate structure that made sense at incorporation but not at your income now. Surfacing these is what the consultation is for.
Are we the right fit?
We work best with physicians whose finances have outgrown a single advisor. Usually that looks like a stack of questions and no clear best path forward. We go deep on the strategy until the plan is clear, the opportunities are on the table, and the risks are managed. We’re probably not the fit if you want the cheapest tax return or reactive advice.
Ready to Get Started?
It’s a paid working session. Bring the corporate question that’s been sitting there. You’ll get a direct answer and a straight read on whether it needs more than one session.